Illustrative report based on a fictional transaction
Project Summit: HVAC services · $2.0M
The buyer’s question
Does a $2.0M HVAC acquisition, financed with an SBA loan and a standby seller note, work for a first-time buyer?
The finding
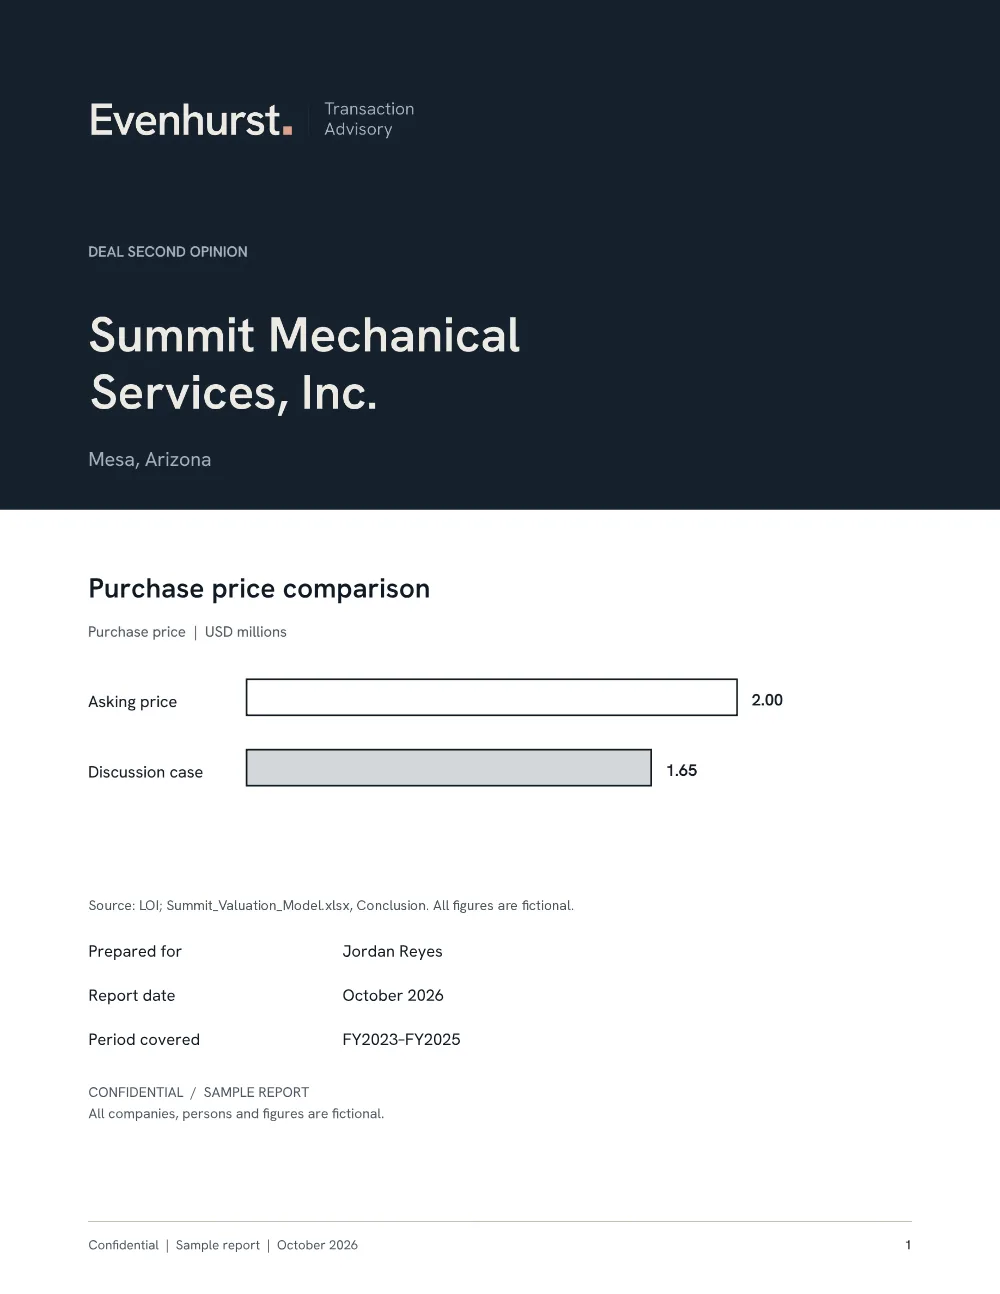
Not at this price. The illustrative analysis supports adjusted SDE of $450.5k, 12.8% below the broker-presented $516.7k. At $2.0M the buyer pays about 4.4x adjusted earnings, above the example’s 3.25–3.75x range, and year-three coverage is 1.245x, below the lender’s 1.25x floor before rounding.
How the analysis supports it
- Market rent, partly supported compensation and personal-expense add-backs, recurring repairs and a warranty reserve: −$66.2k
- Year-three debt service coverage 1.245x; below 1.0x if earnings fall 20%
- Working capital: the deal funds $150k, the business needs about $251k by March, a shortfall of about $101k
- Value from DCF and SDE and EBITDA multiples: $1.65M, within a $1.55–1.75M range
What it changes
Defer signing the LOI in its current form. Use about $1.65M as a discussion price, subject to earnings support, valuation support and lender approval, and arrange separate funding for the seasonal working-capital gap. At that price, illustrated year-three coverage is about 1.51x.
Engagement that produces it
Quality of Earnings, Valuation Analysis and Deal Second Opinion. The same deal is also shown as a Deal Check.
The business is sound. The price and structure are not.